You Built It. Let's Make Sure It Works as Hard as you Did.
You Built It. Let's Make Sure It Works As Hard As You Did.
Financial Planning | Wealth Management | Insurance Planning
September 17, 2026 • 5 min read
A straightforward plan for business owners, real estate investors, and everyday savers who built real wealth — and never got a plan for what to do with it next.
Maybe you own a business, and every dollar it makes goes right back into trucks, payroll, or inventory — because that's what you've always done.
Maybe you've got rental property, and the checks come in every month, but you've never sat down and asked whether that money is actually working as hard as it could be.
Maybe you spent twenty-five years climbing the ladder at a company, and you've got a 401(k), maybe some stock, a good income — and somehow still no real answer to "what happens when the paycheck stops?"
Or maybe you didn't take any of those paths. You just worked, and saved, and never gambled on anything — and you still lie awake some nights wondering if you've actually done enough, or if one bad move could undo all of it.
Different stories. Same problem underneath: you built something real, and nobody ever showed you what to do with it next.
The advice you've been getting wasn't built for you
Most financial advice is written for a different kind of person — someone with a corporate career, a predictable paycheck, and a tidy 401(k) that someone else manages for them. It comes wrapped in jargon, delivered by someone who's never run a business, never missed a payroll, never had to decide between paying yourself and buying the truck the job needs.
If that's not your story, that advice was never going to fit. You didn't build what you have by following a script written for somebody else's career. You built it by taking real risks, doing real work, and making your own calls. You deserve a plan that was actually built for how you got here — not a repackaged version of Wall Street's playbook.
Why I do this work
I've been on both sides of this. Before I started Fish Creek Capital, I spent years in the corporate world — at Regions Bank, supporting executives in technology leadership. I left to build something of my own. I know what it feels like to have real money on the line and no roadmap for what comes next.
That's the reason Fish Creek Capital exists. I'm a fiduciary — legally required to act in your interest, not a commission on my own — and everything I teach, on this blog and on our YouTube channel, is built to be plain language over jargon. No script. Just a straightforward answer to the question every one of these stories shares: where should my next dollar go?
The plan: five kinds of capital you're probably already managing
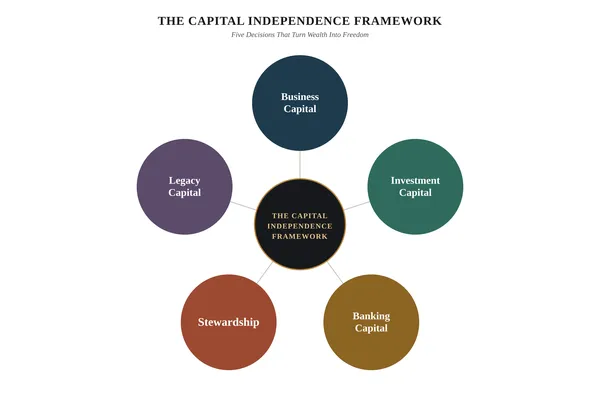
Whether you've thought about it this way or not, if you've built any real wealth, you're already managing five different kinds of capital:
Business Capital — for the business owner: reinvest, pay yourself, or start planning the eventual exit.
Investment Capital — the dollar that's left over, and how it gets put to work so it compounds into a rising stream of income instead of sitting idle.
Banking Capital — a stable, liquid reserve that gives you options without disrupting the money that's already invested and growing.
Stewardship — not just how much you've built, but how you use it. For family. For causes. For the things that actually matter to you — instead of only ever accumulating.
Legacy Capital — what outlives you. What you hand down, and what you make sure never has to be figured out by someone else during a hard week.
I call this the Independence Framework, and it's the same structure whether you're the business owner still reinvesting out of habit, the owner thinking about what happens the day you finally sell, the executive with old 401(k)s scattered across three employers, or the saver who did everything right and just wants to know it's actually enough. The starting pillar is different for each of you. The plan underneath it is the same.
What happens if you don't have one
Nothing dramatic, at first. Money sits a little idle, or a little too concentrated in one place. You pay more in taxes than you need to. There's no real income plan, so "retirement" stays a vague someday instead of a date on the calendar. Years go by. And for some people, it takes one bad decision — or one bad advisor — to undo something that took a lifetime to build.
That's what a real plan is for: so you get to retire on your own terms, on your own timeline, with income that gives you a raise every year no matter what the market's doing — and something real left over to hand down.
Where to start
You don't have to figure this out alone, and you don't have to have it all figured out before you reach out. If you want a simple way to see where your next dollar should go, → download our Dividend Growth e-Book or schedule a free Capital Allocation Conversation— no pitch, just a real conversation about what you've built and what you want it to do next.
You did the hard part already. Let's make sure the money works as hard as you did.
Disclaimer: This article is for informational and educational purposes only and does not constitute investment advice. Past market signals do not guarantee future results. Consult a qualified financial advisor before making any investment decisions. You do not have to move your accounts to work with Fish Creek Capital — we are happy to serve as a resource, second opinion, or planning partner alongside your existing relationships.
financial planning, wealth management, business owner, retirement planning, fiduciary advisor
Jeff Wright
President and Founder of Fish Creek Capital
Jeff Wright is the President and Founder of Fish Creek Capital (Fish Creek Value Management, LLC, CRD #291643), a registered investment advisory firm focused on unlocking financial clarity, confidence, and peace of mind. This content is for educational purposes only and does not constitute personalized investment, tax, or financial advice. Please consult a qualified professional before making investment decisions.